Timber and Joinery sales flat in Q2, says BMBI
Timber and Joinery sales flat in Q2, says BMBI
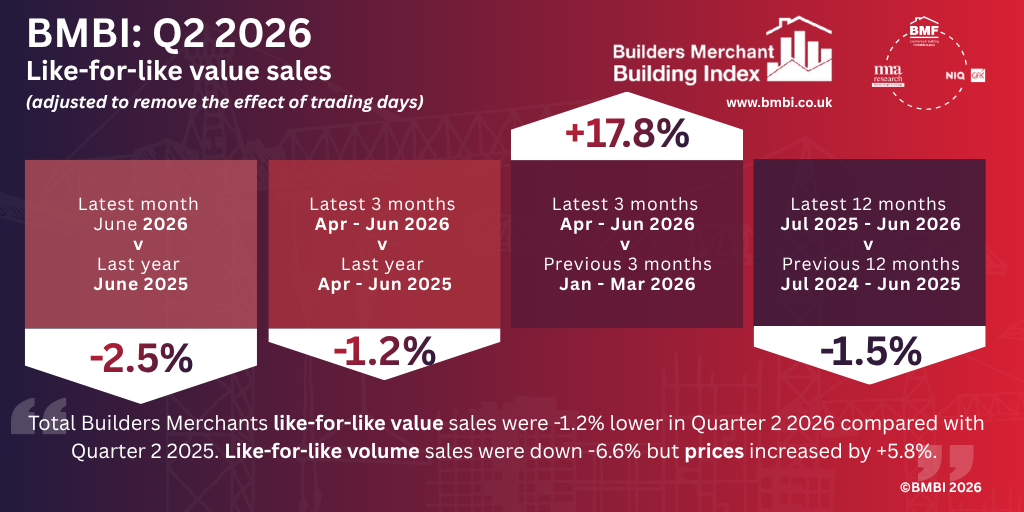
The latest Builders Merchant Building Index (BMBI) report reveals builders’ merchants’ Q2 2026 like-for-like value sales, adjusted to remove the impact of trading days, were -1.2% lower than Q2 2025. Like-for-like volume sales were down -6.6%, but prices increased +5.8%.
With no difference in trading days, unadjusted Q2 total value sales were also down -1.2% year-on-year. Timber and Joinery Products was flat (0.0%).
June 2026 like-for-like value sales were -2.5% lower than June the year before. Like-for-like volume sales fell -10.0% while prices increased +8.4%.
With one extra trading day in June 2026 compared to June 2025, unadjusted total value sales were +2.2% higher year-on-year. Unadjusted volume sales were -5.7% lower and prices were up +8.4%.
In the 12 months July 2025 to June 2026, like-for-like value sales were down -1.5% compared to the previous 12-months (July 2024 to June 2025).
Like-for-like volume sales were down -4.3% but prices increased +2.9%. With no difference in trading days, unadjusted value sales were also -1.5% lower. By unadjusted value, Timber and Joinery Products grew by +1.0%.
James Davenport, Managing Director of Metsä Wood UK and BMBI’s Expert for Softwoods and Engineered Timber said: “Demand for engineered wood products during the second quarter was broadly in line with seasonal averages, indicating that the residential housing market during this period was relatively flat.
“However, some housebuilders are increasing the level of discounting required to maintain their rate of sale, suggesting that underlying market conditions may be slightly weaker than the headline numbers indicate.
“The UK is predominantly a redwood (pine) market, and the imported redwood market has seen a period of relative stability throughout the second quarter.
“Demand and supply are roughly in balance at low levels, however. Sawmills have been supported by a softening of redwood log prices in 2026 but are still at high levels versus historical averages.
“Demand for Nordic whitewood (spruce) remains stronger than for pine and availability is less well balanced.
“Increased demand from Central Europe has placed pressure on the supply of some specifications, with UK buyers increasingly competing with other markets for available material.”
For the latest reports, Expert comments and Round Table Debates, visit: www.bmbi.co.uk.
More news
Donaldson Timber Systems Partners with HebHomes
TJN’s Andy Ball’s day out supporting Lignum members